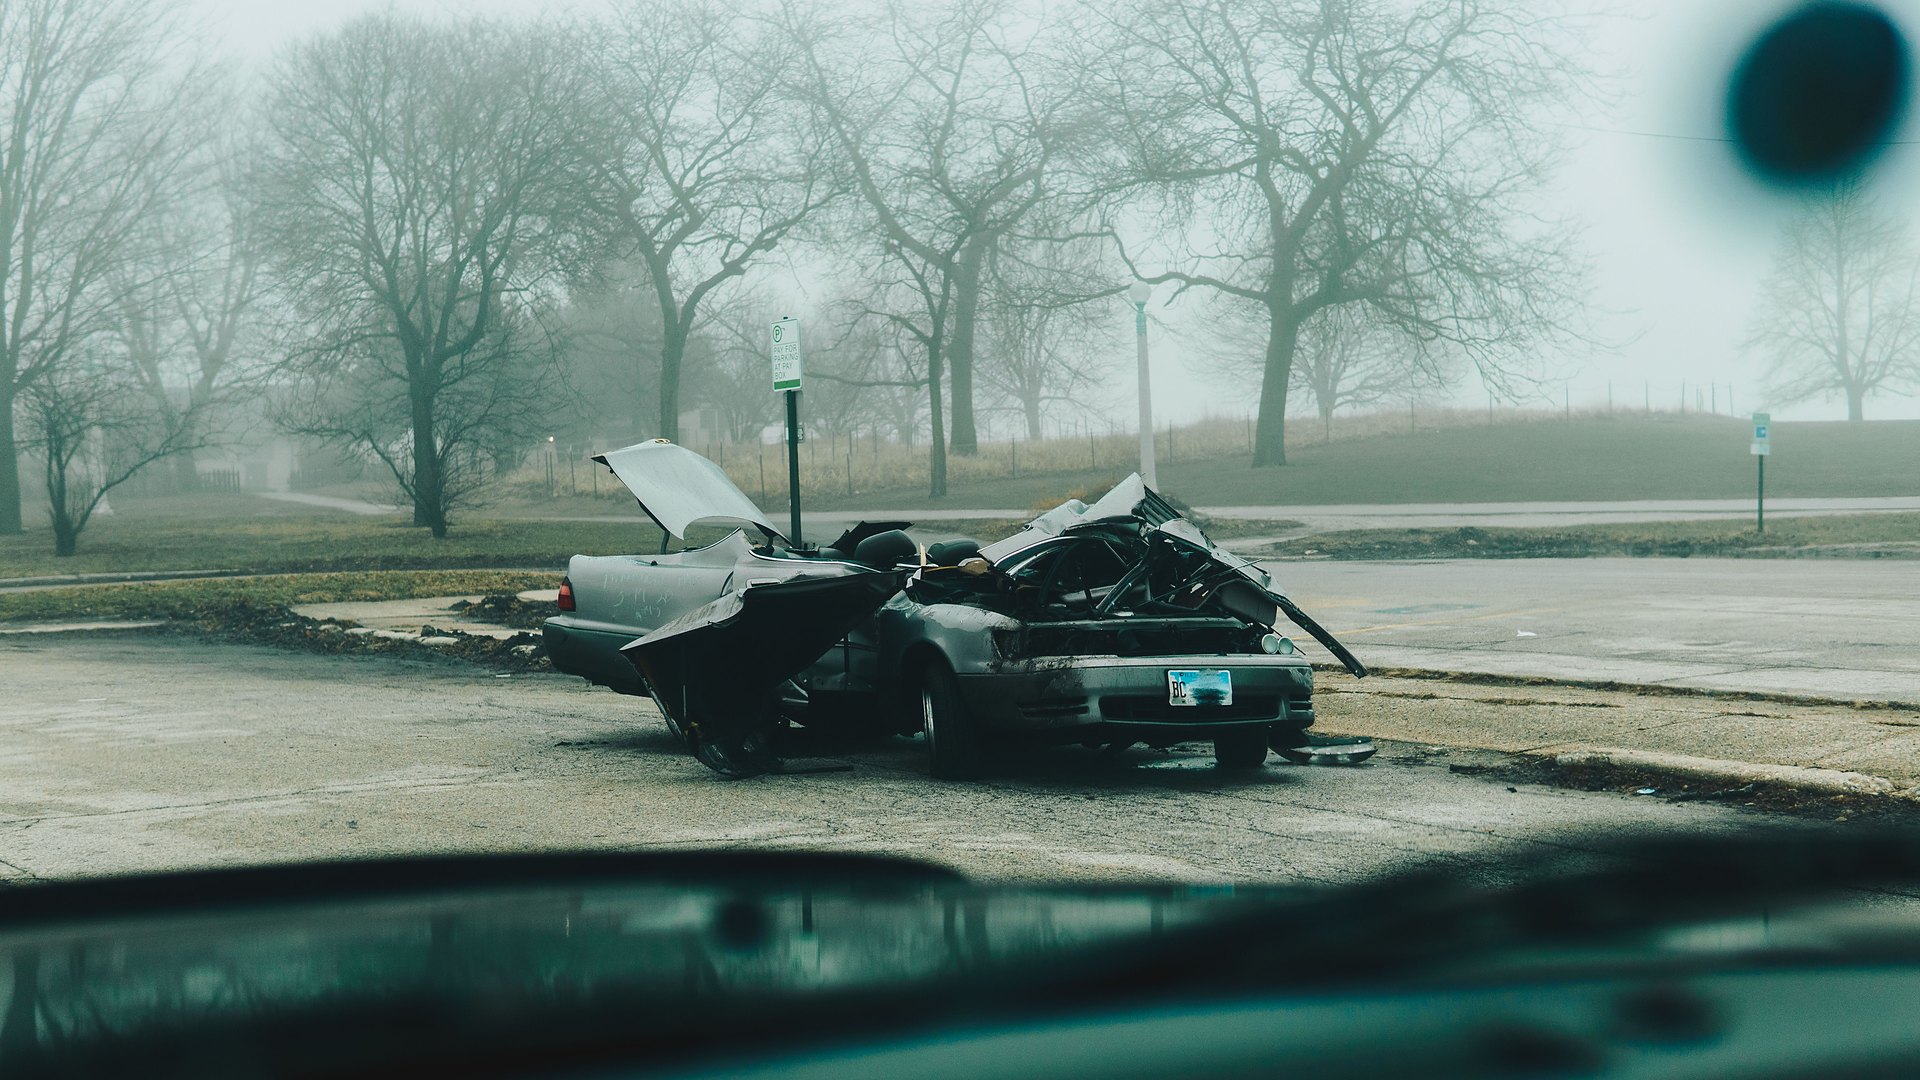
Auto · Uninsured · Underinsured motorist
Your own insurer turned on you.
You pay for uninsured and underinsured motorist coverage for the day someone else can’t pay. When that day comes, too many insurers treat their own customer like the enemy. In Oklahoma, they owe you good faith.
Red flags
Signs they’re playing games.
- A UM or UIM offer that doesn’t come close to your medical bills and lost wages
- A total-loss value well below what your vehicle was worth
- Arguments that your injuries came from something else
- Delays while your bills pile up
What we do
How we fight it.
- 01
Build the full value of the claim: medical, wages, pain and the future
- 02
Challenge vehicle valuations and repair estimates
- 03
Hold your insurer to the same good-faith duty it owes on any first-party claim
Questions
Auto, UM & UIM, answered.
Isn’t my own insurance company on my side?
On a UM or UIM claim, your insurer pays more if it values your claim higher. That’s why the law imposes a duty of good faith and fair dealing.
The other driver had no insurance. What now?
That is what uninsured motorist coverage is for, if you have it. Get your policy declarations and talk to us.
Also
Other fights we take.
Health Insurance Denials
Surgery, medication, rehab or a hospital stay denied. “Not medically necessary.” “Experimental.” “Out of network.”
Fight it
Unpaid & Underpaid Claims
Approved, then never paid. Paid a fraction. Or just ignored. When the insurer won’t pay out.
Fight it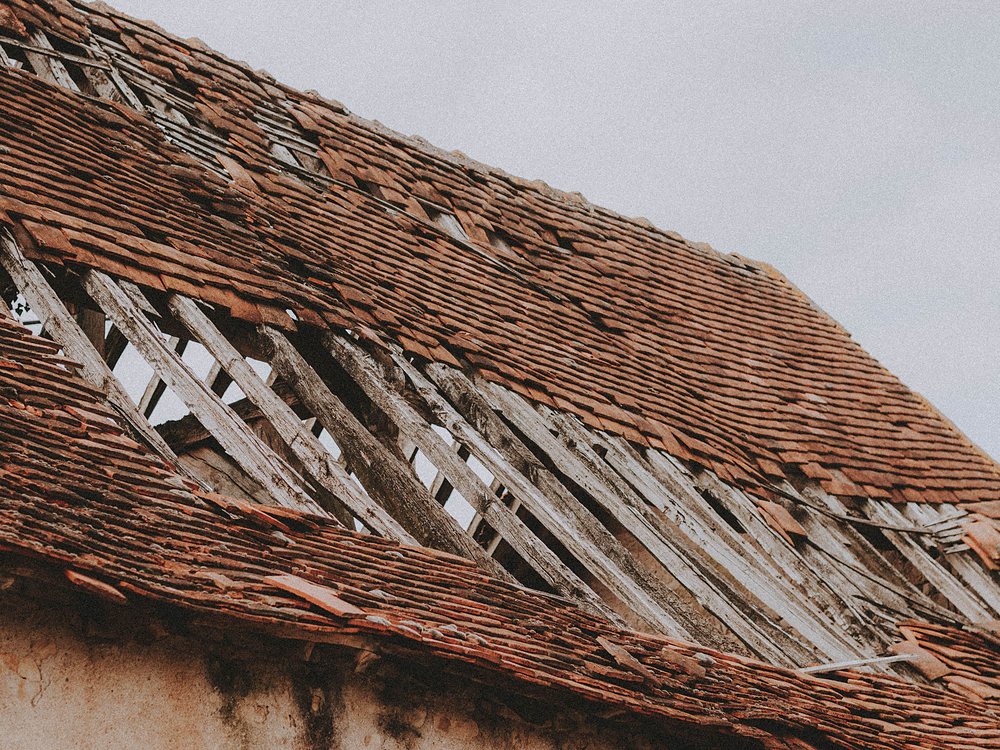
Storm, Hail & Roof
Hail-shredded roof, wind damage, a tornado. Then an adjuster calls it “wear and tear.”
Fight itFree case review
Tell us about your auto, um & uim dispute.
A few sentences is enough to start. We’ll review it and contact you.