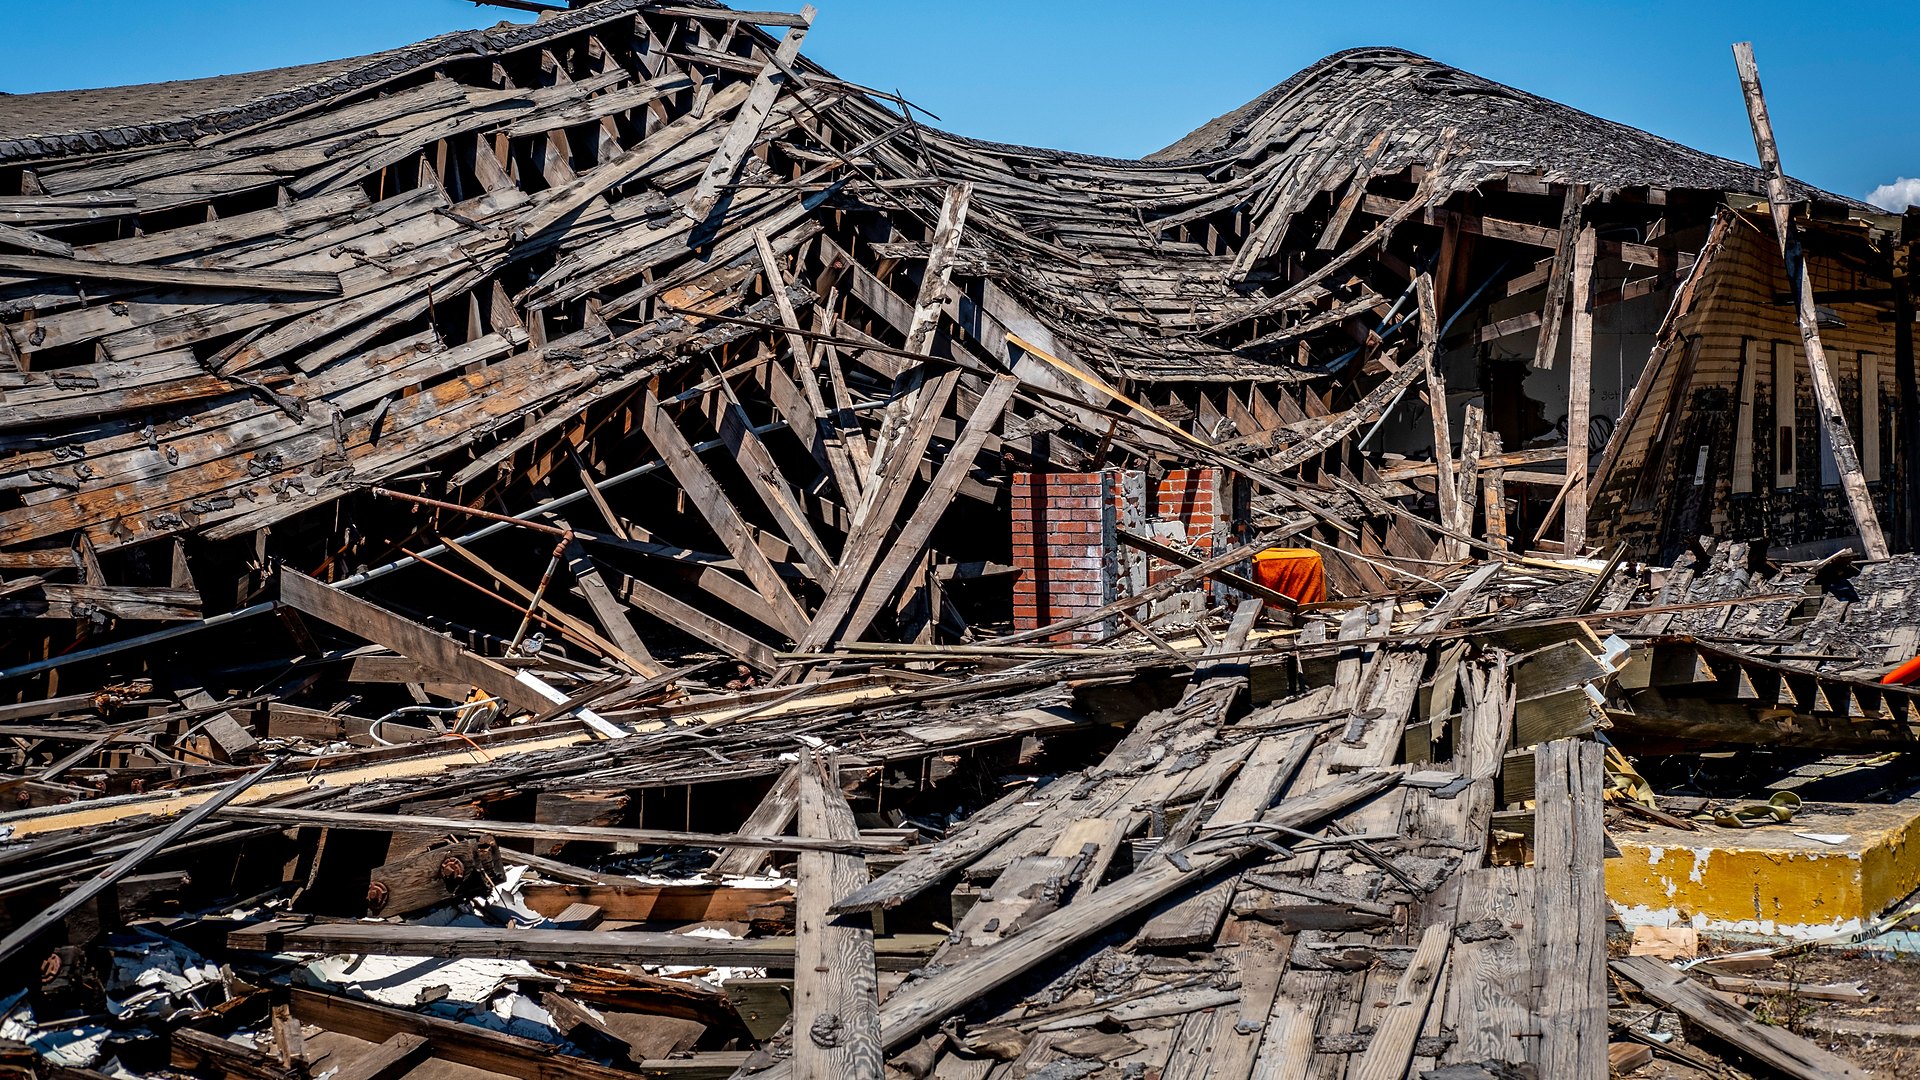
Fire · Water · Theft · Collapse
You paid the premiums.Now make them pay the claim.
A house fire, a burst pipe, a break-in. Homeowners policies are long, and insurers read every exclusion in their own favor. We read the policy the way the law reads it.
Red flags
Signs they’re playing games.
- A denial that points to an exclusion without explaining how it applies
- Contents claims cut to pennies on the dollar with “depreciation”
- Additional living expenses cut off while you’re still out of the house
- Endless requests for the same documents
- A demand for an examination under oath that feels like an interrogation
What we do
How we fight it.
- 01
Read the full policy, endorsements and declarations, not just the denial letter
- 02
Document the loss, the contents and the real cost to rebuild
- 03
Answer their demands on your terms, with counsel at the table
- 04
Hold them to their good-faith duties under Oklahoma law
Questions
Homeowners & Property, answered.
They want me to give a recorded statement. Should I?
Get advice first. Statements and examinations under oath are used to look for reasons to deny.
What if I already got a partial payment?
Partial payment doesn’t end the claim. If it doesn’t cover the loss, the dispute is still open.
Also
Other fights we take.
Health Insurance Denials
Surgery, medication, rehab or a hospital stay denied. “Not medically necessary.” “Experimental.” “Out of network.”
Fight it
Unpaid & Underpaid Claims
Approved, then never paid. Paid a fraction. Or just ignored. When the insurer won’t pay out.
Fight it
Storm, Hail & Roof
Hail-shredded roof, wind damage, a tornado. Then an adjuster calls it “wear and tear.”
Fight itFree case review
Tell us about your homeowners & property dispute.
A few sentences is enough to start. We’ll review it and contact you.